Recognizing whiplash after car accident: When to Get Checked
Free Case Evals · October 4, 2026
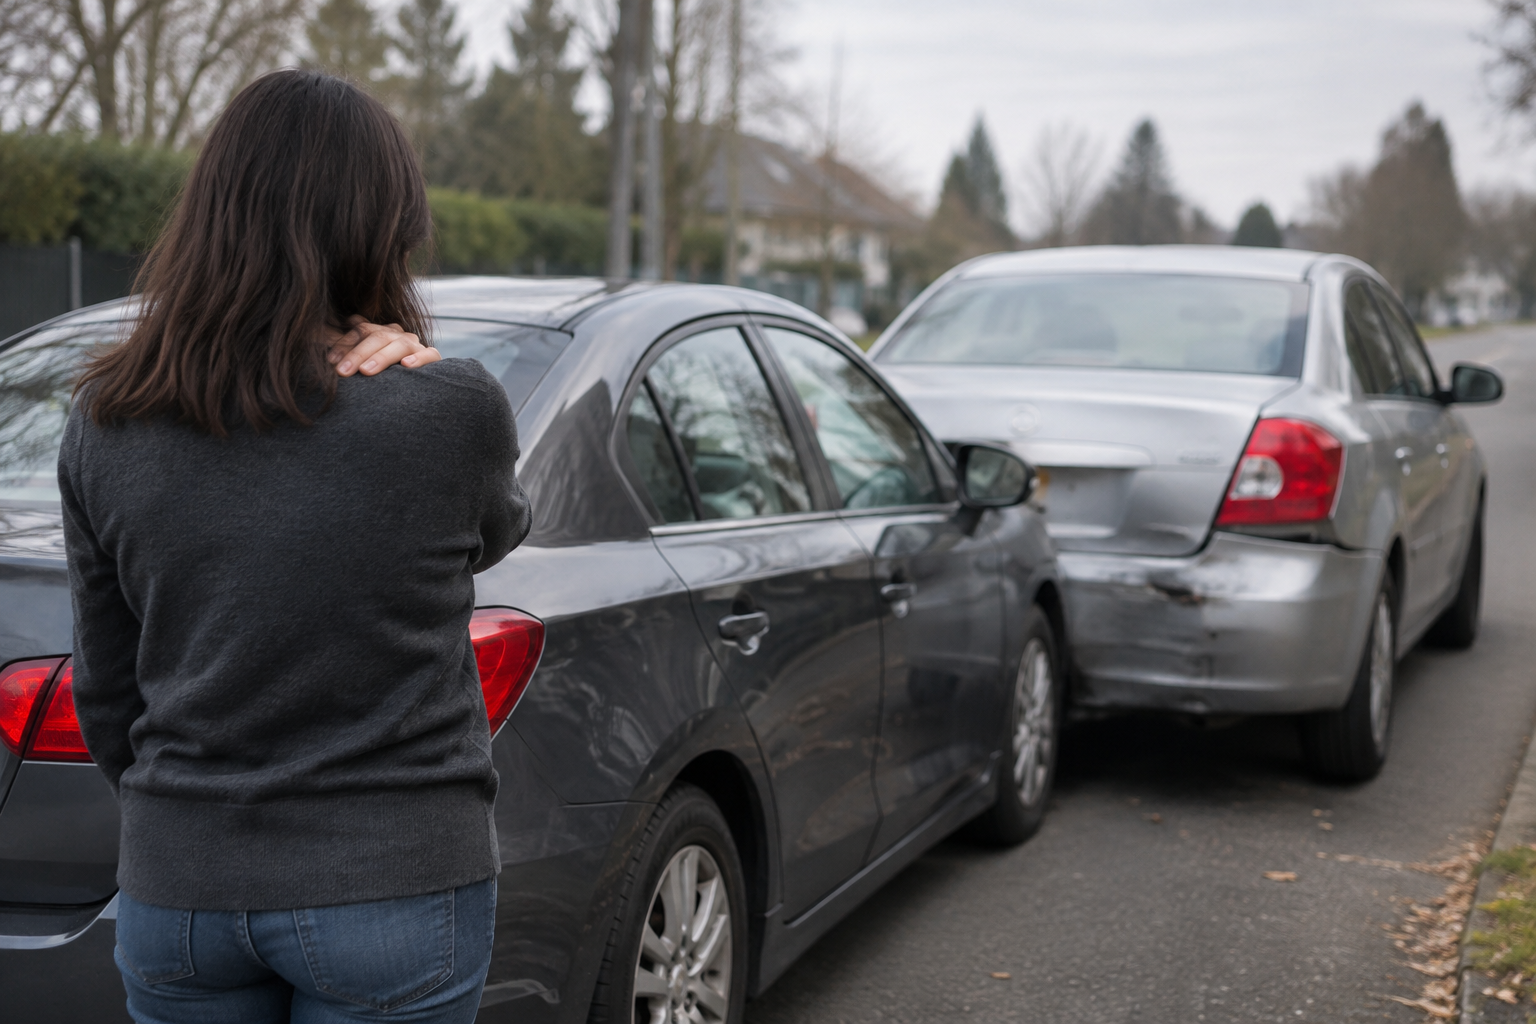
You’re stopped at a light on your way to work when another driver hits you from behind. You exchange information, drive away, and only later notice that turning your head hurts. If you’re searching for “whiplash after car accident,” the short answer is this: neck pain, stiffness, and related symptoms can appear immediately or develop later. A qualified medical provider should evaluate new symptoms promptly because you cannot reliably identify the injury—or rule out something more serious—on your own.
An early evaluation gives you a starting point for appropriate care and creates a record of what you experienced after the collision. It does not guarantee recovery or compensation, and a delay does not automatically defeat a claim. But waiting simply because the bumper looks fine or you hope the soreness will disappear can leave both medical questions and insurance questions unanswered.
What does whiplash after a car accident feel like?
Whiplash describes an injury associated with a rapid back-and-forth movement of the neck. Rear-end collisions are a familiar example, but other crashes can produce similar movement. You do not have to strike your head or lose consciousness to have symptoms that deserve medical attention.
People may notice neck soreness, reduced ability to turn their head, discomfort around the shoulders, or headaches. Some report dizziness or difficulty concentrating. These symptoms are not specific enough to confirm whiplash, and overlapping symptoms can have other causes. Tell a medical provider what you feel rather than deciding on a diagnosis yourself.
Notice changes in ordinary tasks
Sometimes the first sign is practical: checking your blind spot feels difficult, carrying a grocery bag becomes uncomfortable, or sitting at your desk makes your neck ache. Pay attention to those changes without repeatedly testing painful movements.
Before your appointment, write down:
- Where the discomfort is and whether it travels elsewhere.
- When you first noticed it, including whether it started after leaving the scene.
- Which normal activities make it worse.
- Any headache, dizziness, tingling, or other new symptom.
- Whether symptoms are improving, staying steady, or worsening.
A short, accurate description is more useful than a dramatic one. “I woke up with stiffness and could not comfortably look over my right shoulder” tells a provider more than “everything hurts.” Do not minimize symptoms out of embarrassment, but do not exaggerate them to make the crash sound more serious either.
When should you get medical attention for neck pain after a crash?
Seek emergency help for warning signs such as new weakness or numbness, difficulty walking, confusion, loss of consciousness, a severe or worsening headache, or severe neck pain. Trouble breathing or chest pain also calls for immediate attention. This is not a complete list; if symptoms seem serious or you are unsure you can move safely, call emergency services rather than driving yourself.
For less severe neck discomfort, contact a qualified medical provider promptly and explain that you were in a collision. Ask where and how soon you should be evaluated. The appropriate setting depends on your symptoms and circumstances, not on whether an insurer has accepted responsibility.
What if you felt fine at the scene?
Tell the provider exactly that. Symptoms can develop later, and the timing is part of your history. For example, explain that you declined an ambulance because you felt comfortable at the roadside, then developed stiffness that evening. There is no need to rewrite what happened to make your account sound consistent.
If several days have already passed, arrange care now rather than assuming you missed your chance. Explain both the symptoms and the reason for the delay, whether that was lack of transportation, trouble getting an appointment, or believing the discomfort would settle.
Ask the office about costs and available payment options if money is keeping you away. Keep a record of appointment requests and cancellations. Those records do not replace treatment, but they can help explain why care did not begin sooner. Your health should guide the decision to seek care—not a claim strategy.
What happens during a whiplash medical evaluation?
A provider will generally ask about the crash, your symptoms, and your medical history, then perform an examination appropriate to your situation. Describe the collision in plain terms: where you were sitting, which direction the impact came from, whether you wore a seat belt, and whether your head struck anything. Avoid guessing the other vehicle’s speed.
Be open about previous neck discomfort, prior crashes, and any symptoms you had before this one. A prior problem does not automatically prevent a claim for a new injury or an aggravation. Accurate history helps the provider distinguish what changed and reduces avoidable disputes later.
Ask questions before you leave
Useful questions include:
- What changes should make me seek urgent care?
- Is it safe for me to drive or perform my usual work?
- Do I need temporary activity limits or a follow-up visit?
- What should I do if symptoms do not improve?
- Can I get written instructions and any recommended work restrictions?
Not everyone needs imaging. A provider decides whether tests are appropriate based on the history and examination. Imaging may help evaluate certain injuries, but a normal scan does not necessarily explain every source of pain. Do not demand a particular test simply to strengthen an insurance claim.
Follow the individualized plan you receive, and ask before starting exercises or other self-directed treatment. If medication is recommended, ask about side effects that could affect driving or work. Keep discharge instructions, referrals, and appointment summaries together so that another provider can see what has already been assessed.
Why does early medical documentation matter for a whiplash claim?
An insurance claim usually requires more than showing that a crash happened. You may need to establish that the collision caused an injury, that care was reasonably related to it, and that the injury produced financial or personal losses. Medical records can help connect those pieces, although no single visit proves the entire claim.
An early record can document your reported symptoms, examination findings, and recommended next steps close to the event. If the first record appears much later, an insurer may ask whether another event caused the pain or whether the symptoms were significant. A truthful explanation of a delay can matter; it is not a reason to invent an earlier symptom date.
Keep your records accurate, not scripted
Review visit summaries when available. If a record contains a factual error, such as the wrong collision date or an incorrect statement that you had no neck symptoms, ask the office about its correction process. Do not ask anyone to add findings they did not observe.
At follow-up visits, describe changes specifically. Explain whether you can now sleep comfortably, sit longer, or turn your head more easily. Improvement belongs in the record just as much as continued discomfort.
If you are uncertain how treatment records fit into a potential claim, you can request a free case evaluation through Free Case Evals, which connects injured people with participating attorneys. An attorney can discuss the legal documentation questions; your medical provider should decide what care is appropriate.
What should you save to show how the injury affected you?
Start one folder, digital or paper, with separate sections for the collision, medical care, expenses, and work. Save original documents when possible and back up phone photos. A simple system maintained as you go is easier than rebuilding several weeks of events from memory.
Medical costs and other expenses
Keep itemized bills, receipts, insurance explanations of benefits, and records of amounts you paid. An explanation of benefits is not necessarily a bill, so retain both when available. Save receipts for prescribed medication and other provider-recommended items, along with transportation and parking expenses for appointments.
These records help distinguish the amount charged, the amount covered, and any balance still owed. Whether a particular expense is recoverable depends on the claim and state law.
Missed work and daily limitations
For lost income, gather pay statements, schedules, attendance records, and written work restrictions. Ask your employer to document the hours or shifts missed and whether you used paid leave. If you are self-employed, preserve invoices, canceled assignments, and business records that support the claimed loss rather than relying on a rough estimate.
Keep a brief, dated activity log. Record concrete limitations, such as needing help carrying laundry or leaving a shift early because you could not comfortably perform assigned tasks. Note better days too. A diary supports your account but does not replace medical evidence.
Also preserve crash photos, witness contact details, the police report when available, and messages with insurers. Vehicle damage is relevant evidence, but repair cost alone does not determine whether you were injured. For more collision-specific documentation issues, read our guide to claims after a rear-end crash.
Who may pay for medical bills and other whiplash losses?
The available payment sources depend on the policies involved, who was responsible, and state law. Bills may arrive before a liability claim is resolved, so ask about available coverage early instead of assuming the other driver’s insurer will pay every provider immediately.
Potential sources include:
- The responsible driver’s liability insurance: It may cover qualifying losses, subject to fault, policy limits, and other requirements.
- Personal injury protection, or PIP: In states and policies where it applies, it can cover specified losses regardless of fault, subject to limits and conditions.
- Medical payments coverage, or MedPay: If available under an applicable auto policy, it may help with covered medical expenses regardless of fault.
- Health insurance: It may pay covered treatment under the plan’s terms, though coordination and reimbursement issues can arise.
- Uninsured or underinsured motorist coverage: Depending on your policy and state law, it may apply when the responsible driver lacks insurance or sufficient coverage.
Ask about coverage before balances pile up
Request claim numbers, adjuster contact information, and written instructions for submitting bills. Ask providers whether they have the appropriate insurance information and whether any charges remain your responsibility. Do not assume that opening a claim stops collection activity.
Health plans, government benefit programs, or providers may have repayment rights against a recovery. Those issues can affect what you ultimately keep, so raise them with a licensed attorney before settling.
If insurance is missing or insufficient, our article on options when the other driver has no insurance explains additional questions to investigate. A coverage question is separate from proving who caused the crash; both may need attention.
How do insurers evaluate whiplash after a car accident?
Insurers commonly review the collision circumstances, medical records, treatment timeline, prior symptoms, and proof of claimed losses. They may question an injury when visible vehicle damage is limited, symptoms were reported later, or appointments were missed. Those questions do not automatically establish that a claim lacks merit, but they make clear documentation valuable.
When speaking with an adjuster, stick to facts you know. Describe what happened without guessing speed, accepting an unfamiliar medical label, or predicting when you will recover. Keep a dated note of the conversation and request significant coverage decisions or settlement offers in writing.
Be careful with statements, authorizations, and releases
Before giving a recorded statement to another driver’s insurer, consider speaking with a licensed attorney. Your own insurer may have cooperation requirements under the policy, so do not simply ignore its requests. Ask what is required and seek advice if you are unsure.
Review medical authorizations before signing. Understand which providers, dates, and records the form covers. An insurer may legitimately need relevant records, including prior records in some situations, but you should know the scope of permission you are giving.
A quick settlement can be tempting when bills are due. A release may end your ability to seek additional compensation for the same injury even if further care becomes necessary. Before agreeing, understand what claims are being released and whether your likely losses have been assessed.
You can connect with a participating attorney for a free evaluation to discuss an offer or document request. Do not accept or reject an offer solely because it arrived quickly; understand its terms first.
What deadlines and state rules could affect your claim?
The statute of limitations sets a deadline for filing a lawsuit, but it is not the only clock that may matter. Policies can require prompt notice, certain benefits can have application or documentation deadlines, and claims involving government entities may require earlier formal notice. The applicable rules vary by state and circumstances.
Do not assume that ongoing treatment or negotiations pause a filing deadline. Ask a licensed attorney which deadlines apply to your situation, including any separate requirements for insurance benefits. Put identified dates on a calendar and keep proof of submissions.
Fault and benefit rules can change your options
Comparative negligence rules can reduce compensation based on your share of fault. Some jurisdictions use contributory negligence rules that can bar recovery when the injured person shares responsibility, subject to applicable exceptions. Even a rear-end collision should be evaluated on its facts rather than an assumption of automatic liability.
In no-fault systems, PIP may be the initial source for certain benefits, while pursuing a claim against another driver can depend on state-specific requirements. Policy language and coverage limits also affect the available options.
Evidence has its own practical deadline: it can disappear. Nearby business footage may be overwritten, vehicles repaired, and witnesses become harder to reach. Promptly preserve what you can lawfully obtain, and tell an attorney about evidence that may require a formal preservation request. Keep damaged items and original files when practical rather than relying only on edited images or screenshots.
Request a free case evaluation for your whiplash injury questions
You do not need to have every bill, a final diagnosis, or a completed recovery before asking about your legal options. Gather what you already have: the crash date and location, insurance details, photos, medical visit dates, and any letters or offers. Make a short list of unanswered questions, especially about upcoming deadlines, unpaid bills, and requests from adjusters.
Free Case Evals is not a law firm. It is a free service that connects people injured in motor vehicle accidents with participating attorneys for a free case evaluation. This article provides general educational information, not medical or legal advice; laws vary by state, and you should speak with a licensed attorney about your circumstances.
During an evaluation, ask what additional records would help, which coverage might apply, and what deadlines need immediate attention. If you later consider hiring an attorney, ask about fees and costs separately; a free evaluation is not a promise of free representation or a particular result.
Request your free case evaluation when you are ready to discuss the claim. If symptoms are new, worsening, or concerning, contact a qualified medical provider first—an insurance decision should not determine when you get checked.
Frequently Asked Questions
Can a passenger pursue a claim for whiplash after a crash?
A passenger may have a claim against one or more responsible drivers, depending on the circumstances. Auto medical benefits or other coverage may also be available. A licensed attorney can help identify the applicable policies and any state-specific restrictions.
What if the crash happened while I was driving for work?
Workers’ compensation may apply if you were injured while performing covered job duties, and a separate claim against a responsible third party may also be possible. Ordinary commuting and work-related travel can be treated differently. Report the incident through the appropriate workplace process and ask an attorney about coordinating benefits.
Can I change medical providers after an accident?
You can ask about changing providers or getting a second opinion, but insurance networks, referrals, and certain benefit programs may affect coverage. Arrange for relevant records to follow you so the new provider has an accurate history. Explain the reason for the change and avoid an unnecessary interruption in recommended care.
What should I do if an insurer denies my whiplash claim?
Request the denial and its stated reasons in writing, and keep the envelope or electronic delivery record. A coverage denial, a dispute over fault, and a dispute over medical expenses may require different responses. Ask a licensed attorney about review options and deadlines rather than assuming the denial is final.
Should I post about my accident on social media?
Public posts, photos, and comments may be reviewed in connection with a claim and can lose context when viewed separately. Avoid discussing injuries, fault, or settlement negotiations online. Do not delete potentially relevant existing posts without asking an attorney about evidence-preservation obligations.
This article is for general informational purposes only and is not legal or medical advice. Laws vary by state. Speak with a licensed attorney about your specific situation.
Hurt in a car accident?
Answer a few quick questions to see if you may qualify for a free case evaluation. No cost, no obligation.
Start My Free Case Evaluation